

Fox is turning Fear Factor into a scripted vertical series for My Drama, while RisingJoy is building a 30-title slate of AI-assisted vertical anime. New Short Media has produced one project in both mobile episodic and theatrical formats. Channel 4, Disney+, Lionsgate, Banijay and Japanese anime companies are also reshaping how entertainment is financed, licensed and distributed.
⦿⦿
One story no longer belongs to one screen. The leverage lies with whoever controls the rights, the audience relationship and the next transaction.
Week of Oct 26-Nov 01, 2026
That used to mean adapting a successful film or television series after the audience had already arrived. This week, the format decisions came earlier. Fox rebuilt an unscripted franchise as a scripted vertical series. RisingJoy tied an AI-assisted anime slate to international distribution. New Short Media shot one project for mobile episodes and a feature film at the same time.
The pattern extends beyond production. Unions are arguing over who must license the material behind AI systems. Broadcasters are placing live channels inside global streaming apps. Anime companies are investing in the machinery that sells rights overseas.
The commercial question is becoming sharper: when a story moves between screens, who keeps the rights, the audience relationship and the next transaction?
Fox rebuilds Fear Factor as scripted vertical IP
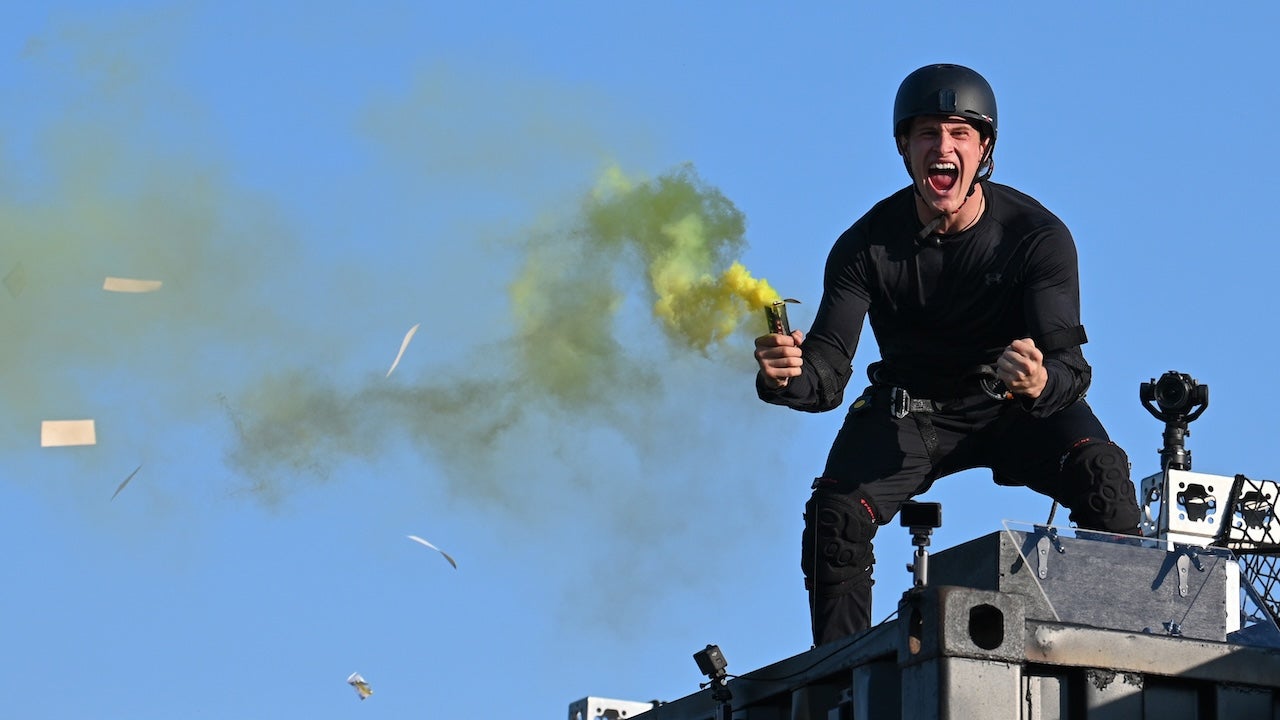
Fox Entertainment Studios and Endemol Shine North America are producing a 30-part scripted vertical series inspired by Fear Factor for Holywater’s My Drama platform. Each horror episode will run approximately three minutes, with Fox Entertainment Global handling worldwide distribution.
Fox calls this its first conversion of an unscripted television franchise into an original scripted extension. Unlike a recut or promotional spin-off, the series changes the genre, episode length and viewing environment while keeping the underlying brand.
For Fox, it is a contained way to find out whether an established franchise can bring viewers into mobile fiction. My Drama gets a recognizable title without having to introduce an unknown world from scratch. Neither party has disclosed the economics or future adaptation rights, and audience retention will determine whether the experiment travels. The important move has already happened: vertical drama has entered Fox’s franchise-development process.
 Tess Patton
RisingJoy connects AI production to a 30-title anime slate
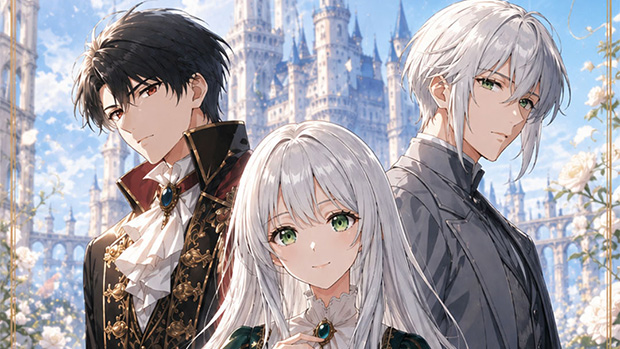
RisingJoy plans to complete 30 AI-assisted vertical anime titles under its RJOY Originals label by the end of the first quarter of 2027. Six are complete in Japanese and English; RisingJoy says AI helps sustain the volume within short-form budgets.
RisingJoy and NTT DOCOMO Studio & Live signed a memorandum covering non-exclusive international licensing on a title-by-title basis, initially targeting Southeast Asia and other markets outside Japan.
On paper, the combination is unusually concrete: a production target, two languages, a delivery window and a sales route. The announcement does not explain budgets, staffing, training data or audience performance. Those omissions matter, especially when AI is being credited with making short-form economics possible. If the titles arrive on schedule, RisingJoy will have tested something more useful than a demo: whether AI can sustain a recurring slate and whether Japanese storytelling can travel in a mobile-native format.
 Nico Franks
New Short produces one story in two formats
New Short Media has completed production on It’s My Party & I’ll Die If I Want To as both a vertical episodic series and a horizontal feature film. The horror comedy is part of an inaugural slate of roughly 10 projects.
No platform, distributor or financing structure has been announced, so there is no evidence yet that the approach improves the economics. What New Short has demonstrated is a production choice: design for mobile viewing and longer-form distribution before the cameras roll.
The attraction is obvious. Sets, performers and development work can serve two products, while response to one version may help sell the other. The risks are just as practical: competing edits, unclear positioning and additional delivery costs. Distribution will reveal whether the two versions feel native to their screens or whether one is simply a compromise built from the other.
 Neil Batey
JLA Play gives DramaBox a local route into France
French streaming service JLA Play has agreed to carry approximately 30 DramaBox microdramas, primarily romance and relationship-led series. The companies did not disclose financial terms, but JLA says the partnership supports its ambition to become France’s first independent platform dedicated to vertical fiction.
France will test whether a local service can sell microdrama differently from a global app. DramaBox gains a route to viewers through an established French brand; JLA gets enough imported titles to programme a category before building a large original slate.
No financial details were released, and localization, marketing and audience ownership will decide whether this becomes more than a library deal. The structure is still notable. Instead of buying every user directly, an international short-drama company is using a territory-specific partner. That gives licensing a larger role in a business dominated by direct-to-consumer apps and paid acquisition.
 Hannah Whitcombe
Entertainment unions push AI training toward licensing
SAG-AFTRA, WGA West, WGA East and AFM have asked to file a joint amicus brief in The New York Times copyright case against OpenAI and Microsoft.
The unions say copyrighted work should not receive blanket fair-use protection when used for generative AI training. They cite licensing income, residuals and collectively bargained AI terms as evidence of a market for permission and compensation.
What the guilds want recognized is a market, not only an injury. Licensed training could produce income through contracts, residuals and royalties; unlicensed training bypasses it.
The court may reject that argument, and this filing will not create a universal rule for AI training. It does, however, move the dispute closer to everyday entertainment economics. The question is becoming less theoretical: who can authorize a work’s use, what permission costs, and whether the people who created it share in the transaction.

Lionsgate uses partner capital to expand production risk
Lionsgate and Steven Paul’s SP Media have formed a new joint venture majority-owned and controlled by Lionsgate. SP Media will invest an undisclosed sum in new ventures, 3 Arts Entertainment’s diversification and independent films distributed by Lionsgate.
This is studio finance by bolt-on. SP Media gains access to an established distribution system; Lionsgate gains capital without carrying every expansion entirely on its own balance sheet. It also keeps operational control and a position across production, representation and library value.
The missing number matters. Without the investment amount, project commitments or return structure, it is impossible to judge the venture’s scale. The design is nevertheless revealing. Lionsgate can widen its slate and test adjacent businesses without committing to permanent overhead, while an outside partner absorbs part of the risk. In a tight financing market, that flexibility may be more useful than simply adding another corporate acquisition.
 Lionsgate
Channel 4 moves its public-service offer inside Disney+
Channel 4 and Disney will place a Channel 4 streaming offer inside Disney+ in the UK and Ireland from early 2027. It will include the broadcaster’s live HD channel, hundreds of on-demand hours and selected shows released simultaneously on both services.
Disney+ is not merely licensing a group of programmes. It is adding a broadcaster’s live feed and branded environment to its own interface. Channel 4 keeps its identity and standalone service while gaining access to viewers who may no longer begin with a broadcaster app.
That convenience creates a harder question for Channel 4: does greater reach strengthen its direct audience relationship, or make Disney+ the more important gateway? The answer sits in undisclosed terms covering data access, advertising and prominence. The deal is an ambitious distribution shortcut, but the party controlling discovery may capture more of its long-term value.
Overseas demand becomes the centre of anime economics
Japan’s anime industry reached an estimated ¥4.45 trillion in 2025, or roughly $28.2 billion to $28.5 billion. Preliminary figures presented by the Association of Japanese Animations at TIFFCOM showed 15.8% annual growth, with overseas revenue rising 17.2% to roughly $16.1 billion.
International business represented 57.1% of the market. Overseas demand is now the larger side of the industry, not an export tail attached to domestic success. Selling anime therefore depends as much on rights discovery, localization and coordinated release windows as on adding production capacity.
The headline number does not show how much reaches studios, publishers or creators. It explains why licensing platforms and multilingual distributors are attracting capital. Demand is already proven at global scale. The harder job is moving more titles through the market—and returning enough value to the companies making them.
 Matt Schley
Banijay reorganizes for scale and digital-first demand
Banijay UK is folding North One into Optomen as a label, refocusing Objective Media Group on scripted programming and moving entertainment formats to genre specialists. It is also establishing Banijay Scotland after combining with All3Media.
Banijay linked the changes to a commissioning market that increasingly rewards programmes of scale and digital-first ideas. The immediate logic is efficiency: remove overlaps, concentrate genre expertise and give the enlarged group a clearer regional base.
This is the unglamorous part of consolidation, when a merger begins to change who develops what. Shared resources may help labels survive a tighter market. They can also reduce the number of independent production identities. Banijay now has to show that its labels retain creative authority, not only access to a larger group. The reorganization will be judged by the programmes it produces—not by the neatness of the new chart.
 Bo-Larz Davies
AniBiz turns anime licensing into shared infrastructure
Anime licensing platform AniBiz has raised $6 million in seed investment from TBS Group, Toei Animation and TV Tokyo Holdings. The company has opened registration to verified buyers worldwide and says its marketplace represents more than 30 licensors, up from 20 when the platform launched in July.
TV Tokyo disclosed a $2 million investment. More telling than the amount is the choice by three Japanese media groups to support one shared marketplace instead of building separate sales routes for every company and title.
The practical work is difficult. AniBiz must verify buyers, standardize rights information across territories and windows, and produce enough completed deals to keep licensors active. Those are transaction problems, but they determine whether smaller rights holders can reach overseas distributors without a large international sales team. The investment fits the week’s anime data neatly: global demand is already large; access to that demand remains uneven.
 Nakama, Inc.
Also This Week
- Viaplay completed the €142 million sale of its Dutch business. The disposal to DPG Media’s Videoland is expected to generate approximately €100 million in net cash after costs and legacy payments. Viaplay will use the proceeds to reduce debt and concentrate on its Nordic operations.
- Versant expanded its FAST portfolio to 13 channels. Four new channels drawing on CNBC, Oxygen and E! brands launched on Prime Video, with Roku distribution to follow. The move converts established cable franchises into free, advertising-supported streaming inventory outside the traditional pay-TV bundle.
- The News Movement launched TNM Network. The business will license documentaries from creators and YouTube producers, then repackage them for TikTok, Instagram and other platforms while preserving creator identity. Original commissions are planned for 2027, positioning TNM between distributor, network and creator-services company.
- Non-English titles dominate major streamers’ acquired content. Ampere Analysis found that 65% of Netflix acquisitions and 50% of Disney+ acquisitions came from non-English markets. The figures cover licensed titles in at least one territory, excluding platform originals and in-house production.
- Liverpool’s Littlewoods production campus received conditional government backing. The United Kingdom pledged £20 million, subject to approval of a final business case, toward a 260,000-square-foot creative complex. The project could add studios, innovation and education facilities, but still faces funding and delivery risks.
Further Reading
The Quiet Takeover: How AI Is Rewriting the Short Drama Playbook — Its examination of AI-generated microdramas moving through real distribution and monetization systems provides the production context for RisingJoy’s slate and Fox’s continued work with HOLYWATER TECH.
 Real Reel
Amazon, Disney, Netflix All Have Vertical Feeds Now. What Happens to the Rest of the Industry? — Its analysis of vertical feeds and library repackaging extends this week’s question about how IP moves between mobile, broadcaster and streaming interfaces.
 Real Reel
✱